AI & business · Field notes
Does AI Leave You More Money From the Same Creative Job?
For a freelance content producer: follow one flyer from brief to job costs, distinguish supplier profit from your own, and stop paying to sort endless drafts.
- Written
You are a freelance content producer with a flyer to deliver and another client waiting. AI gives you more versions than you asked for. Now you have to pick one, fix the details and find out whether the extra attempts ate the money you were supposed to keep.
I want AI to get a useful piece of work off your plate. If it makes the image quickly but leaves you sorting drafts all afternoon, the generation price tells you very little.
Take this fictional client brief: one portrait flyer for Afterlight Supper Club. The supplied details are a three-course Mediterranean supper, October 24 at 7 PM, $65, Afterlight House, 8 Sample Court. Menu and dietary options belong at booking. The client has not supplied a booking link or the event year.
Your first assignment to the AI Hire is small: organize those supplied details, flag the gaps, and prepare one draft for review. It should carry the same brief into generation rather than ask you to explain the job again. This is an illustrative workflow, not a completed client project. The flyer below is a sample, not proof of a sale.
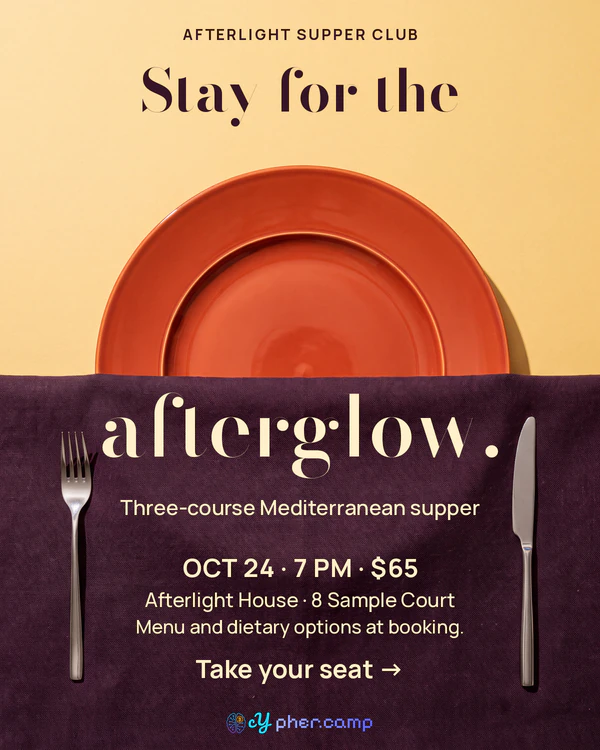
You still check the offer, date and artwork before client approval. The missing booking link stays missing. An AI Hire should ask for it, not invent a destination behind “Take your seat.” Check the year too; the picture does not settle it.
That gives you a useful handoff: the brief, one draft, the supplied facts beside it, and the questions that actually need you. Once a format is approved, repeated resizing and filename checks can be candidates for a tested routine. Taste, rights and client promises still need someone responsible for them.
But a useful flyer and a profitable job are different questions. The client pays you. You pay for generation, subscriptions and your time. I build at the application layer with cYpher.camp, so I have the same problem: a customer payment is revenue, and the costs decide what remains.
Compare the same accepted flyer
For the same fee, AI leaves you more only if the accepted job costs less to finish, without lowering the standard. Use your own job record to decide whether the tool earns its place. The industry figures later can help you understand who you are paying.
Job cost card: suppose the agreed fee for this fictional flyer is $200. Compare your current process with using AI to deliver the same accepted portrait flyer: the same approved offer and facts, readable copy, cleared artwork rights and agreed export, with the missing year and booking link resolved by the client before release. Keep that acceptance standard and the $40 hourly value of your time the same in every row. These are illustrative worksheet inputs, not a cYpher price, measured earnings or a completed client job.
Count all the time in both methods: briefing, preparation, failed attempts, sorting drafts, editing, checks and client revisions. Include the job’s share of tools and subscriptions, plus generation charges where used. The totals below include that work; they do not start the clock after the difficult part is over.
Current-process row: $200 fee − (4 hours × $40) − $5 in tools = $35 selected-cost remainder.
AI row: $200 fee − (3 hours × $40) − $12 in generation and subscriptions = $68 selected-cost remainder. Against the current process, $68 − $35 = $33 more after those selected costs. That is an illustrative difference, not measured savings or net profit.
AI overrun row: if the same accepted flyer takes 5 hours, $200 − (5 × $40) − $12 = −$12. Compared with the current process, −$12 − $35 = −$47. The extra attempts have left you $47 worse off on these inputs, even though the tools still cost only $12.
I would want to see those whole-job totals before calling the AI version cheaper. In your own card, an unknown time or cost stays unknown until you record it. Do not fill the gaps with these example numbers and call the difference a result.
That is a project comparison, not accounting net profit. It leaves out other overhead, interest and taxes, and the value you put on your time may differ from an accounting expense. The supplier figures in the optional investigation below use reported net income. Do not mix the two measures.
Try the brief before buying an image
For the first test, use the fictional brief and an assistant you already have. Ask it to return the supplied facts, unanswered questions, one draft brief and a job cost card with unknown costs marked unknown. No automatic retries, publishing, customer messages, purchases or access to client files. Before any metered generation, set a spending cap the tool can enforce; an instruction in chat is not a billing control.
Try the missing booking link and event year deliberately. A useful assistant brings those questions back instead of guessing. Give it only assets you have the rights and permission to use. Check the output and obtain client approval before release. The first test can stop at the brief; you do not have to buy an image to see whether it understood the job.
If that handoff works, save the brief format, approved style, export requirements and the rule for when to stop. After testing the connections and checks, you can authorize routine preparation or approved-format exports without reviewing every intermediate step. Keep records, a working pause and exceptions for missing facts, rights questions, changed offers or cost overruns. That removes repeated setup decisions; it does not authorize new client promises or turn on publishing.
For your next job, fill in the same rows with what it actually took. Count accepted deliverables, total costs, revision time and the decisions that still come back to you. Stop generating alternatives once the agreed draft is good enough. More versions are not extra value if you are the one paying to sort them.
At cYpher.camp, our hosted cYpher.claw agents work with the customer’s instructions, connected tools and approval boundaries. Plans and AI credits pay for that work. We still have to earn our place over using the same model somewhere else. The brief above does not mean those client connections are already installed.
And then we have to cover generation, hosting, storage, support, development and the rest of running the business. The customer's payment is our revenue. The costs decide whether there is a profit. I believe useful AI businesses can be built. I am building one. But I do not get to skip that last part because I believe in the technology.[1]
If the same accepted flyer costs less to finish and I spend less time chasing it, I would keep the routine. If the old process does the job better, I would keep that.
Optional investigation: who profits behind the app?
That is also what I wanted to understand about the bigger AI industry. Who earns actual profit after expenses, interest and taxes? I suspected NVIDIA might be the only one. Several suppliers report profits, and older AI software has a counterexample too. Their results do not tell us whether your next flyer will pay for itself.
Amazon, Microsoft, Google’s parent Alphabet and Meta are planning more than $700 billion in capital spending in 2026, much of it to build the infrastructure behind AI.[2]
Seven hundred billion dollars. From four companies.
For scale, that’s more than Sweden’s entire 2025 GDP. Spread $700 billion across a year and it’s nearly $2 billion every single day.[3]
Those are planned capital costs, not a count of profitable creative jobs. Follow the bill beneath this one flyer and you can see why buying AI and making money with it are separate decisions.
The bill doesn't stop at the app
You do not need to buy a server to make this flyer. An application can pay a provider to run a model; that provider can rent computing capacity. Someone supplies the machines, electricity and cooling. Each business charges a customer and pays its own bills.
Those bills do not all come out of the same payment at the same moment. Equipment may have been bought long before you needed this flyer. Investors and lenders can fund a business while its customer payments are still too small to cover its costs. Adding every company's revenue together would count parts of the same spending more than once.
CoreWeave operates on the expensive side of that arrangement. It buys and operates computing equipment, then rents capacity to AI labs and other customers. Its customers get to use the machines without owning them. CoreWeave takes on the equipment, facilities, financing and operating costs.
For 2025, CoreWeave reported a US$1.17 billion net loss on US$5.13 billion in revenue. There were paying customers. There were billions in sales. There was still a loss.
That is why I am using reported net income as the profit test here. Revenue is sales. Net income is the accounting result after expenses, interest and taxes. GAAP and IFRS are accounting rules used to prepare those statements. A revenue headline tells us people are buying. It does not tell us the business works yet.[4]
The seller and the buyer
Now look at a company selling CoreWeave the machinery. NVIDIA reported US$120.07 billion in net income for its fiscal year ending January 25, 2026. One company sells the computing equipment at a profit overall. The other buys and operates equipment, sells access to it, and reports a loss overall.
Two companies can ride the same AI boom and end up on opposite sides of the bill.
NVIDIA still has an expensive business to run. Designing processors, arranging manufacturing and maintaining the software around them all cost money. But the company buying its systems has another job after they arrive: keep them running, find enough paying work for them, and cover the financing. Owning something everyone wants to use does not guarantee you bought it at a price that makes your business profitable.[5][6]
NVIDIA has suppliers too
But stopping at NVIDIA leaves out the businesses that make its part of the chain possible. NVIDIA designs chips. TSMC manufactures them. Memory companies provide the fast access to data those processors need. Power and cooling suppliers help keep the whole installation running.
Take the memory. Buying a powerful processor does not help much if it spends its time waiting for data. SK hynix sells the high-bandwidth memory that helps feed those processors. The company says AI demand and its shift toward higher-value products helped improve profitability. It reported ₩42.95 trillion in consolidated net profit for 2025.
That gives me a reason to look past NVIDIA. The equipment buyer needs more than a processor, and another business can earn a profit supplying what goes beside it. Micron tells a similar story about AI demand, memory sales and tight supply improving profitability. NVIDIA can win an order without being the only supplier that benefits.
It extends beyond memory. TSMC makes the chips; Vertiv supplies power and cooling equipment; Broadcom designs custom chips and networking. All report company net profits in the periods listed below. Their jobs differ, but each supplies something the companies running AI need to buy.
Those company results still do not tell me the exact profit from AI alone. SK hynix and Micron are explaining what helped their businesses, not publishing separate after-tax accounts for AI. NVIDIA has the same limit: its US$120.07 billion is profit for the whole company, and Data Center revenue is broader than AI.
Think about your own work. A profitable studio might earn money on flyers and lose money on video revisions. Knowing the total does not tell you which job pays the rent. The profits of Amazon, Microsoft and Alphabet cannot tell us whether a particular chatbot pays for itself either.
So I can say profitable suppliers are benefiting from the buildout. I cannot take all of their earnings and label them AI profit. And I cannot give NVIDIA that shortcut while denying it to everyone else.[7][8]
Does the money ever stay with the software?
Following the bills toward the machines made my original suspicion look too narrow. It also suggested another one: maybe the physical suppliers make the profit while the software companies spend it.
Appier prevents me from turning that into a rule. It sells AI advertising and marketing software and reported audited net profit of 2.558 billion Japanese yen for 2025, after finance costs and taxes. It spreads some development costs over future years, so that profit is not cash left after all investment. But under the same net-income test, a software business passes too.
But Appier was founded in 2012, before ChatGPT and the current generative AI boom. AI includes systems that make predictions and recommendations. Generative AI creates text, images and other content. A profitable advertising-software business does not prove that training a frontier model or selling image generations is profitable too.
Closer to the flyer itself, Midjourney's founder said the company was profitable in a 2022 interview. Venice's CEO told TechCrunch his company was profitable in July 2026. I could verify those statements. I could not verify comparable net-profit amounts from financial statements. The older Midjourney statement also cannot tell us what it earns today.
For OpenAI, Anthropic, DeepSeek, Mistral and Moonshot, the sources checked for this guide did not give me a verified net-profit result. Zhipu reports an annual loss. That leaves us with different answers for different businesses, not proof that every app or model lab loses money. Unknown means I do not have the answer.[9][10][11][12][13]
As a content producer, you can get a useful draft while a company behind it loses money. NVIDIA, SK hynix, Micron, TSMC, Broadcom and Vertiv reported company profits in the periods reviewed. Appier provides an older AI software example from before the generative AI boom. The strongest link I found between the buildout and improving profitability was among physical suppliers, particularly memory. None of that establishes their exact profit from AI alone, or proves that only hardware makes money. Unverified results remain unknown.
Reference: the 43 company profiles
To make life easy, here are 43 companies I've been tracking in AI. It's not an exhaustive list, but it covers some important players and how they fit into the AI economy.
The machines and factories behind the chips
Before a model can answer a question, someone has to make the machinery that makes the chip. A new app cannot bypass that work just by being easier to use.
ASML — (Nasdaq: ASML; Euronext Amsterdam: ASML)
Builds the extraordinarily precise machines that print chip designs onto silicon. Chip factories buy the equipment, upgrades, and servicing. Reproducing that engineering is much harder than launching another chatbot on an existing model.
FY2025 (ended 2025-12-31): €9.61 billion net income; revenue €32.67 billion.[14]
TSMC — (NYSE: TSM ADS; TWSE: 2330)
Runs the factories that turn other companies’ chip designs into working processors, then packages advanced chips together. Designers pay for manufacturing. NVIDIA designs chips; TSMC manufactures them. Those are different businesses, and TSMC can supply several competing designers.
FY2025 (ended 2025-12-31): NT$1.70 trillion consolidated net income, under IFRS as issued by the IASB; revenue NT$3.81 trillion.[15]
Processors, memory and complete systems
A server order contains several businesses. NVIDIA and Dell both report net profit, but sell different parts of that system. These are company-wide results, not AI-only margins.
NVIDIA — (Nasdaq: NVDA)
Sells AI processors, networking, systems, and the software ecosystem around them. Clouds and companies buy this machinery to train models and run them for users. Its advantage is not just a fast chip: developers and infrastructure teams have built around its tools. That makes switching a project, not a simple shopping decision.
FY2026 (ended 2026-01-25): US$120.07 billion net income; revenue US$215.94 billion. Data Center revenue was US$193.7 billion, a category broader than AI alone. This is NVIDIA’s company-wide profit, not a separately reported AI-only net-profit figure.[16]
AMD — (Nasdaq: AMD)
Sells AI accelerators and server processors, alongside PC and other chips. It gives buyers an alternative to NVIDIA. Switching still means making the hardware and software work for the job; the chip price is only part of that decision.
FY2025 (ended 2025-12-27): US$4.34 billion net income; revenue US$34.64 billion.[17]
Broadcom — (Nasdaq: AVGO)
Helps big cloud companies build custom AI chips and sells networking that connects computing clusters. It also owns a large infrastructure-software business. The custom-chip business lets customers build for their own workloads instead of buying only general-purpose accelerators.
FY2025 (ended 2025-11-02): US$23.13 billion net income; revenue US$63.89 billion.[18]
Arm — (Nasdaq: ARM ADS)
Licenses processor designs and collects royalties when customers ship chips using its technology. That puts it inside products sold by many other companies. It also announced its own data-center CPU in 2026.
FY2026 (ended 2026-03-31): US$904.00 million net income; revenue US$4.92 billion.[19]
SK hynix — (KRX: 000660)
Makes memory, including the high-bandwidth memory that feeds AI accelerators. A powerful processor waiting for data is wasted capacity. Buyers pay for memory that keeps up. Making the memory is difficult, which can support prices. But sales still rise and fall, and factories are expensive.
FY2025 (ended 2025-12-31): ₩42.95 trillion consolidated net profit; revenue ₩97.15 trillion. Audited K-IFRS figures.[20][21]
Micron — (Nasdaq: MU)
Sells memory and storage chips used in servers and devices. AI needs both. The factory spending and memory-supply cycle still matter when I look at how much of those sales becomes profit.
FY2025 (ended 2025-08-28): US$8.54 billion net income; revenue US$37.38 billion.[22]
Samsung Electronics — (KRX: 005930)
Makes memory, manufactures chips, and sells devices. A customer might buy a component, pay Samsung to manufacture a design, or buy a finished phone. The figures cover Samsung Electronics and its subsidiaries, not the entire Samsung conglomerate.
FY2025 (ended 2025-12-31): ₩45.21 trillion net income; revenue ₩333.61 trillion.[23][24]
Dell — (NYSE: DELL)
Turns processors, memory, storage, and networking into complete systems businesses can deploy. Customers buy servers, support, and other hardware.
FY2026 (ended 2026-01-30): US$5.94 billion net income; revenue US$113.54 billion. Within that total, AI-optimized-server revenue was US$24.68 billion.[25][26]
Supermicro — (Nasdaq: SMCI)
Builds servers, racks, and cooling systems. Customers need usable installations, not a pile of expensive components. Manufacturing, inventory and delivering those installations all cost money before an order turns into profit.
FY2026 (ended 2026-06-30): US$2.23 billion consolidated net income; revenue US$39.06 billion. These are the audited financial-statement figures; the auditor separately issued an adverse opinion on internal controls.[27]
Power and cooling
More processors are useful only if a facility can power and cool them. These suppliers can serve the buildout without predicting which assistant people will prefer.
Vertiv — (NYSE: VRT)
Sells power and cooling equipment and services for data centers. More computing creates heat and power-delivery problems, and operators pay to solve them. Vertiv supplies the equipment; it is not an electricity utility.
FY2025 (ended 2025-12-31): US$1.33 billion net income; revenue US$10.23 billion.[28]
Schneider Electric — (Euronext Paris: SU)
Supplies electrical distribution, energy management, automation, and data-center systems. Buildings and industrial customers also buy its products, so the figures include much more than the AI buildout.
FY2025 (ended 2025-12-31): €4.16 billion net income, group share; revenue €40.15 billion.[29][30]
Cloud and infrastructure
Here customers rent computing instead of building a facility. Some suppliers also sell software, devices or advertising; the group accounts include those businesses too.
CoreWeave — (Nasdaq: CRWV)
Rents GPU capacity to AI labs and other customers. The operator takes on the bills that renting lets the customer avoid: equipment, facilities and the costs of running them. Depreciation and interest also weigh on its results.
FY2025 (ended 2025-12-31): US$1.17 billion net loss; revenue US$5.13 billion.[31][32]
Microsoft — (Nasdaq: MSFT)
Gets paid through Azure computing, business software and Copilot products. It already sells to many of the companies buying AI. An employer can add AI to that existing relationship instead of introducing a new supplier.
FY2026 (ended 2026-06-30): US$133.75 billion net income; revenue US$331.84 billion. Azure revenue exceeded US$100 billion across AI and non-AI cloud services; Azure-only net profit is not given.[33][34]
Amazon/AWS — (parent Amazon — Nasdaq: AMZN)
AWS rents computing and sells managed AI services. Amazon also develops its own AI chips and models. AWS can earn money serving different model providers and enterprise customers. Amazon’s overall numbers also include shopping, logistics, advertising, and much more.
FY2025 (ended 2025-12-31): US$77.67 billion net income; revenue US$716.92 billion. AWS alone: US$45.61 billion operating income and US$128.73 billion revenue. AWS reports operating income, not net profit; its figures include non-AI computing.[35][36][37]
Alphabet/Google — (parent Alphabet — Nasdaq: GOOGL Class A / GOOG Class C)
Owns Google, whose AI business spans Gemini, custom TPU chips, cloud services, search, and workplace software. Advertisers, businesses, developers, and subscribers pay different parts of the company. Google can sell AI directly and use it to protect or improve businesses it already has.
FY2025 (ended 2025-12-31): US$132.17 billion net income; revenue US$402.84 billion.[38][39][40]
Oracle — (NYSE: ORCL)
Sells databases, business software and rented cloud infrastructure, including AI computing. Its results are a useful warning: a company can report net profit while spending more cash on its buildout than operations bring in. A signed commitment is not cash in hand, though some customers prepay or supply the GPUs.
FY2026 (ended 2026-05-31): US$17.09 billion consolidated net income; revenue US$67.36 billion. Cloud infrastructure revenue was US$18.1 billion, including AI and non-AI workloads. Company free cash flow was negative US$23.69 billion; that is a separate cash-flow measure, not a net loss.[41][42][43]
Huawei — (private; no public stock ticker)
Sells telecom equipment, devices, computing chips, cloud services and other infrastructure. A business can buy several parts of its technology setup from Huawei rather than assemble separate suppliers. The accounts cover that broader business.
FY2025 (ended 2025-12-31): RMB68.04 billion net income; revenue RMB880.94 billion.[44][45]
Baidu — (Nasdaq: BIDU ADS; HKEX: 9888)
Sells advertising and enterprise cloud services while developing models and autonomous driving. Search and cloud give it existing customers for AI products. I would want to know whether newer AI sales add to the business or replace something it already sold.
FY2025 (ended 2025-12-31): RMB5.46 billion net income; revenue RMB129.08 billion.[46][47]
AI inside an existing business
Apple and Meta can use AI to help sell a device or an advertisement. Tencent has similar routes through its existing platforms. Tesla's company profit does not prove its robotics work makes money.
Apple — (Nasdaq: AAPL)
Sells devices and services, with AI integrated into its hardware and operating systems. Some AI runs on the device; some uses cloud services. Apple does not need every customer to buy a separate chatbot subscription for AI to help its business. It can make the device more useful and worth keeping.
FY2025 (ended 2025-09-27): US$112.01 billion net income; revenue US$416.16 billion.[48][49][50]
Meta — (Nasdaq: META)
Advertisers pay for access to people using Facebook, Instagram, and its wider ecosystem. AI supports recommendations, advertising, and consumer products; Meta also releases Llama models. A free assistant can serve an advertising business. That is different from a lab depending on paid model calls.
FY2025 (ended 2025-12-31): US$60.46 billion net income; revenue US$200.97 billion.[51][52][53]
Tencent — (HKEX: 0700)
Runs consumer platforms, gaming, advertising, payments and enterprise services. Like Meta, it can put AI inside businesses that already have customers. A paid standalone assistant is only one possible way to earn from it.
FY2025 (ended 2025-12-31): RMB229.80 billion net income; revenue RMB751.77 billion.[54][55]
Tesla — (Nasdaq: TSLA)
Earns revenue from vehicles, energy products and services while funding autonomous driving and robotics. The figures cover the existing business; they do not show whether robotics is profitable.
FY2025 (ended 2025-12-31): US$3.79 billion net income attributable to common shareholders; revenue US$94.83 billion.[56][57]
The companies building the models
The labs have to pay to run today’s models and build the next ones. That is why I want the bottom line after the sales announcement. Several groups here span more than one layer; their company results should not be mistaken for one model’s profit.
OpenAI — (private; no public stock ticker)
Makes the models behind ChatGPT and sells subscriptions, developer access and enterprise products, including coding tools.
Net profit not verified. Bloomberg reported on August 13, 2026 that annualized revenue exceeded US$40 billion, citing people familiar with the matter. Reported run rate, not completed-year sales.[58][59]
Anthropic — (private; no public stock ticker)
Claude Code gives Anthropic a way into work developers repeat every day. The company sells Claude through subscriptions, developer access and enterprise tools.
Net profit not verified. CNBC reported on August 17, 2026 that Anthropic told investors its annualized revenue run rate reached US$65 billion at July-end. Reported run rate, not completed-year sales.[60][61]
SpaceX/xAI — (Nasdaq: SPCX; xAI’s parent)
SpaceX acquired xAI in February 2026 and completed its Cursor acquisition in August. Customers now pay the group for launches, Starlink connectivity, Grok, X, rented AI computing, and coding software. Owning more layers creates more places to charge, but it also combines very different costs. Scale alone does not tell us which activity earns its keep.
Six months ended 2026-06-30: US$4.82 billion consolidated net loss; revenue US$12.51 billion. Unaudited GAAP statements, not a full year. The AI segment generated US$3.38 billion revenue, including advertising, subscriptions and infrastructure; that is not Grok-only sales or AI-segment net profit. These results predate the completed Cursor acquisition.[62][63][64]
DeepSeek — (private; no public stock ticker)
Offers paid model access and downloadable model weights. Developers can pay for hosted use or operate eligible models themselves. Estimates of training costs or the margin on serving a model do not tell us whether the whole company is profitable.
Net profit and company revenue not verified. Unknown does not mean zero or a loss.[65][66][67]
Alibaba/Qwen — (parent Alibaba — NYSE: BABA ADS; HKEX: 9988)
Alibaba combines commerce and cloud computing with the Qwen model family. Qwen can attract developers and businesses that then pay Alibaba for hosting and related services. That makes a model useful to a much larger business even when downloading its weights is free.
Fiscal year (ended 2026-03-31): RMB102.13 billion net income; revenue RMB1023.67 billion. Cloud segment revenue was RMB158.13 billion, not Qwen-only sales.[68]
Mistral AI — (private; no public stock ticker)
Sells model access, Vibe subscriptions (formerly Le Chat), and enterprise deployments, with downloadable weights for some models. Customers can pay for hosting and business support even when model weights are available to download.
Net profit not verified. CNBC reported annualized revenue above US$400 million in January 2026. In a September interview, its CEO declined to give an updated revenue figure; US$1 billion remained an expectation.[69][70][71][72]
Moonshot AI/Kimi — (private; no public stock ticker)
Builds Kimi and sells assistant subscriptions, developer access and enterprise services. Developers can use its models while paying for the convenience of a hosted service.
Net profit not verified. TechCrunch, citing Bloomberg, implies an August 2026 annualized revenue run rate of US$1 billion: its reported year-end US$2 billion target was double the August pace. The August figure is derived from that comparison; the year-end target is not achieved revenue.[73][74]
Zhipu AI/GLM — (HKEX: 2513 — Knowledge Atlas)
Builds GLM models and sells cloud services and customer-controlled deployments. Also known as Knowledge Atlas Technology, it listed in Hong Kong in January 2026. Unlike most private labs here, it gives us a reported annual loss to inspect.
Fiscal year (ended 2025-12-31): RMB4.72 billion net loss; revenue RMB724.33 million.[75]
Applications, data and business tools
Here the customer pays for something closer to finished work: code, research, a creative asset or a business process. This is also where cYpher.camp fits. Our hosted agents work with the customer’s instructions, connected tools and approval boundaries. The test I care about is whether the product remains useful when its underlying model is also available to a competitor.
Cursor/Anysphere — (parent SpaceX — Nasdaq: SPCX)
Cursor, built by Anysphere and now part of SpaceX, sells developers a code editor and coding agents that work with their codebase and development tools. It integrates outside models and develops its own. Customers pay for the coding experience around the model. The acquisition completed on August 14, 2026.
Standalone net profit not verified. Reuters reported roughly US$2.6 billion in annualized business-to-business revenue in June 2026, citing company data. A B2B subset and pre-acquisition snapshot, not total-company annual sales.[76][77]
Venice — (private; no public stock ticker)
Sells subscriptions and developer access to several AI models. Privacy is part of its pitch; its policy includes third-party processing and temporary storage of generated video.
Profitability claimed by its CEO; net-profit amount and audited accounting basis not verified. On July 1, 2026, its CEO told TechCrunch the company was profitable and annualized revenue exceeded US$70 million. The token's market value is not company revenue.[78][79][80]
Perplexity — (private; no public stock ticker)
Sells AI research, answers and agent tools to consumers and businesses. It wants to be where people start a question or a task. Reliable answers, computing costs and content rights all matter to whether that becomes a profitable business.
Net profit not verified. Sacra estimates an August 2026 annualized revenue run rate of US$750 million. Third-party estimate, not audited annual sales.[81][82]
Hugging Face — (private; no public stock ticker)
A hub where developers share and discover models, datasets and tools. It charges for collaboration features, hosting and computing services. NVIDIA announced an agreement to acquire Hugging Face on September 3, 2026. The announcement does not mean the deal has closed.
Net profit and company revenue not verified. Its paid products show how it charges; the acquisition price is not revenue or profit.[83][84][85][86]
Databricks — (private; no public stock ticker)
Helps businesses organize, govern and use their data for analytics and AI. Customers pay for platform usage. Getting the right business information to a model is useful work in its own right.
Net profit not verified. Company disclosure, August 13, 2026: revenue run rate above US$7 billion, including the data business. Positive adjusted free cash flow does not establish net income.[87][88]
Snowflake — (NYSE: SNOW)
Sells a cloud data platform with analytics and AI capabilities. Customers pay as they use it. That usage brings both revenue and infrastructure costs; the reported bottom line here is a loss.
FY2026 (ended 2026-01-31): US$1.33 billion net loss; revenue US$4.68 billion.[89][90]
Salesforce — (NYSE: CRM)
Sells customer-management software and AI tools such as Agentforce to sales and service teams. It can add AI to software those teams already use.
FY2026 (ended 2026-01-31): US$7.46 billion net income; revenue US$41.53 billion.[91][92]
ServiceNow — (NYSE: NOW)
Sells enterprise workflow software, including AI features. Businesses already use it to route requests and manage work. That gives it a place to add AI where the next action happens, rather than leave an employee copying a chatbot’s answer into another system.
FY2025 (ended 2025-12-31): US$1.75 billion net income; revenue US$13.28 billion.[93][94]
Adobe — (Nasdaq: ADBE)
Sells creative, document and marketing software, with generative AI inside established tools. Creators pay for the working environment as well as the output. Being where the project already lives gives Adobe an advantage, though a better way to finish the work can still pull customers elsewhere.
FY2025 (ended 2025-11-28): US$7.13 billion net income; revenue US$23.77 billion.[95][96]
Palantir — (Nasdaq: PLTR)
Businesses and governments pay Palantir to connect their data with the decisions and work they need to carry out. The product includes software and help deploying it.
FY2025 (ended 2025-12-31): US$1.63 billion net income; revenue US$4.48 billion.[97][98]
IBM — (NYSE: IBM)
Sells enterprise software, consulting and infrastructure, including AI tools. Companies pay for the technology and help making it work inside their organizations. Its AI “book of business” includes measures other than recognized revenue; I use the financial statements for the profit question.
FY2025 (ended 2025-12-31): US$10.59 billion net income; revenue US$67.54 billion.[99][100]
Source note: This is a dated educational guide, not an investment recommendation or a ranking. Financial lines use reported GAAP/IFRS results where established, not adjusted earnings. Company disclosures and third-party estimates are labeled separately. Public earnings releases may be unaudited; historical figures can be restated. Figures do not isolate AI profitability unless explicitly stated.